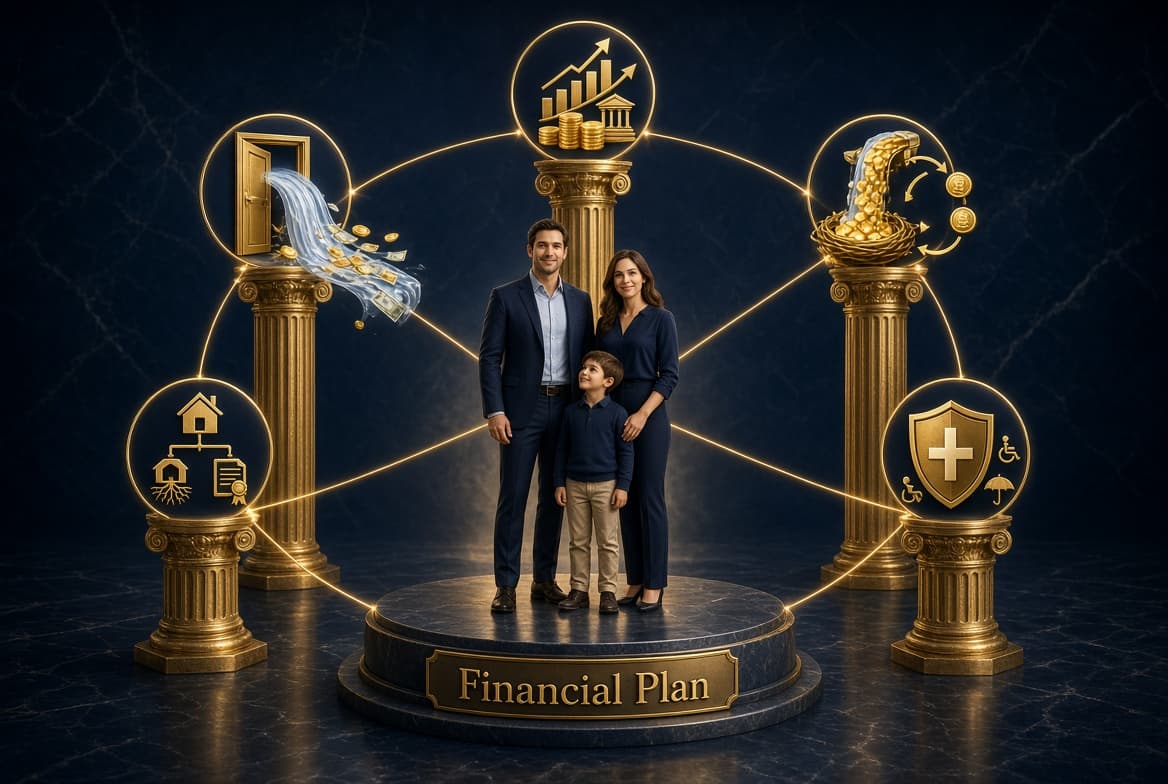
Financial planning has increasingly been reduced to one question: Where should I invest my money?
Stocks, cryptocurrency, real estate and stories about “what rich people do” dominate the media. While these assets may have a place in a financial strategy, the constant noise can distract people from a more important question:
How well does my entire financial plan work together?
The financial stories that attract attention are usually about extraordinary investment gains. We hear far less about families whose plans collapsed because of illness, disability, excessive debt, poor tax planning or the absence of proper insurance and estate documents.
A strong financial plan is a system. Just as we cannot declare one organ of the body more important than all the others, we should not evaluate our finances using investment returns alone.
Your plan should pass five essential tests.
- The Growth Test
Is your money growing at the rate required to achieve your goals?
Growth should not mean moving one step forward and two steps backward. It requires an appropriate investment strategy, disciplined contributions, reasonable costs and a plan to gradually reduce risk as your time horizon becomes shorter.
Markets provide potential returns, but investor behaviour determines how much of those returns an individual actually captures.
DALBAR’s investor-behaviour research has repeatedly found that average investors can underperform market benchmarks because of poorly timed buying and selling. For example, in 2024, the S&P 500 returned 25.02%, while the average equity investor earned 16.54%. The long-term gap is not always as dramatic, but the evidence supports an important principle: emotional decisions can significantly reduce investment results. DALBAR
Growth is therefore not merely a market event—it is also a behavioural outcome. A capable advisor can help investors maintain discipline, understand risk and avoid making permanent decisions because of temporary market conditions.
- The Alternative-Access Test
If a valuable opportunity appeared today, could you access capital without abandoning your existing long-term strategy?
Many people build assets but have no flexibility. To fund a business, property or other opportunity, they may have to sell investments at the wrong time, create an unexpected tax bill or take on expensive debt.
A robust financial plan should include liquidity and, where appropriate, responsible access to leverage. The objective is not to borrow unnecessarily. It is to ensure that all your capital is not trapped in places that are difficult or costly to access.
- The Distribution Test
Accumulating money and converting it into reliable income are different challenges.
Your plan must answer: When employment income stops, how easily can these assets produce sustainable income? What taxes will apply? How will withdrawals be coordinated during market downturns? Could your income last throughout retirement?
An impressive account balance does not automatically create a dependable retirement. Distribution must be designed before it becomes necessary.
- The Estate Test
If you died today, would your assets transfer efficiently to the people and causes you care about?
A plan may accumulate significant wealth and still fail if taxes, legal costs, poor beneficiary designations or the forced sale of assets erode the estate.
Wills, powers of attorney, beneficiary designations, insurance and business-succession arrangements should work together. Estate planning is not only about transferring assets—it is about preserving their value and directing them intentionally.
- The Health-Challenge Test
If illness or disability interrupted your income today, would your financial plan support you—or would you have to dismantle it?
Consider an RRSP. An ordinary withdrawal is generally taxable and subject to withholding tax. However, an eligible first-time homebuyer may withdraw up to $60,000 through the Home Buyers’ Plan without immediate tax withholding, provided the program’s conditions and repayment requirements are met. Canada Revenue Agency
Yet there is no comparable general RRSP withdrawal program simply because someone becomes critically ill. Without emergency savings and appropriate health, disability or critical-illness protection, a person may be forced to withdraw taxable retirement assets during an already difficult period.
That is why protection must be part of financial planning—not treated as an afterthought.
Build Beyond the Noise
A truly holistic plan examines cash flow, debt management, emergency reserves, protection, asset accumulation, retirement distribution and estate preservation.
The best person to help you during a financial crisis is often the person you were before the crisis—the version of you who planned ahead.
Do not allow investment noise to make your plan one-dimensional. Returns matter, but so do liquidity, income, protection and legacy.
Your financial plan should not only help you prosper when everything goes right. It should also protect your progress when life does not go according to plan.
That is the difference between simply owning investments and having a truly robust financial plan.